MTN / FQ4 2026 - Jul 2026
Vail Resorts, Inc.
Reports Sep 28 · After close
Publication status
Shortcut loss
Sep 28, 2026, 9:00 AM PDT
Shortcut
-5.63
Off by $0.29 per share
-4.8% vs Street
Street
-5.37
Off by $0.03 per share
Real
-5.34
Normalized diluted · USD per share
Reported result
Vail’s normalized diluted EPS was -$5.34 for the quarter ended July 31, 2026, reported on September 28. Shortcut was off by $0.29 per share, compared with $0.03 for the Street.
Vail Resorts earnings release ↗Explore the model.
Explore the assumptions and calculations behind this earnings forecast.
What drives the forecast
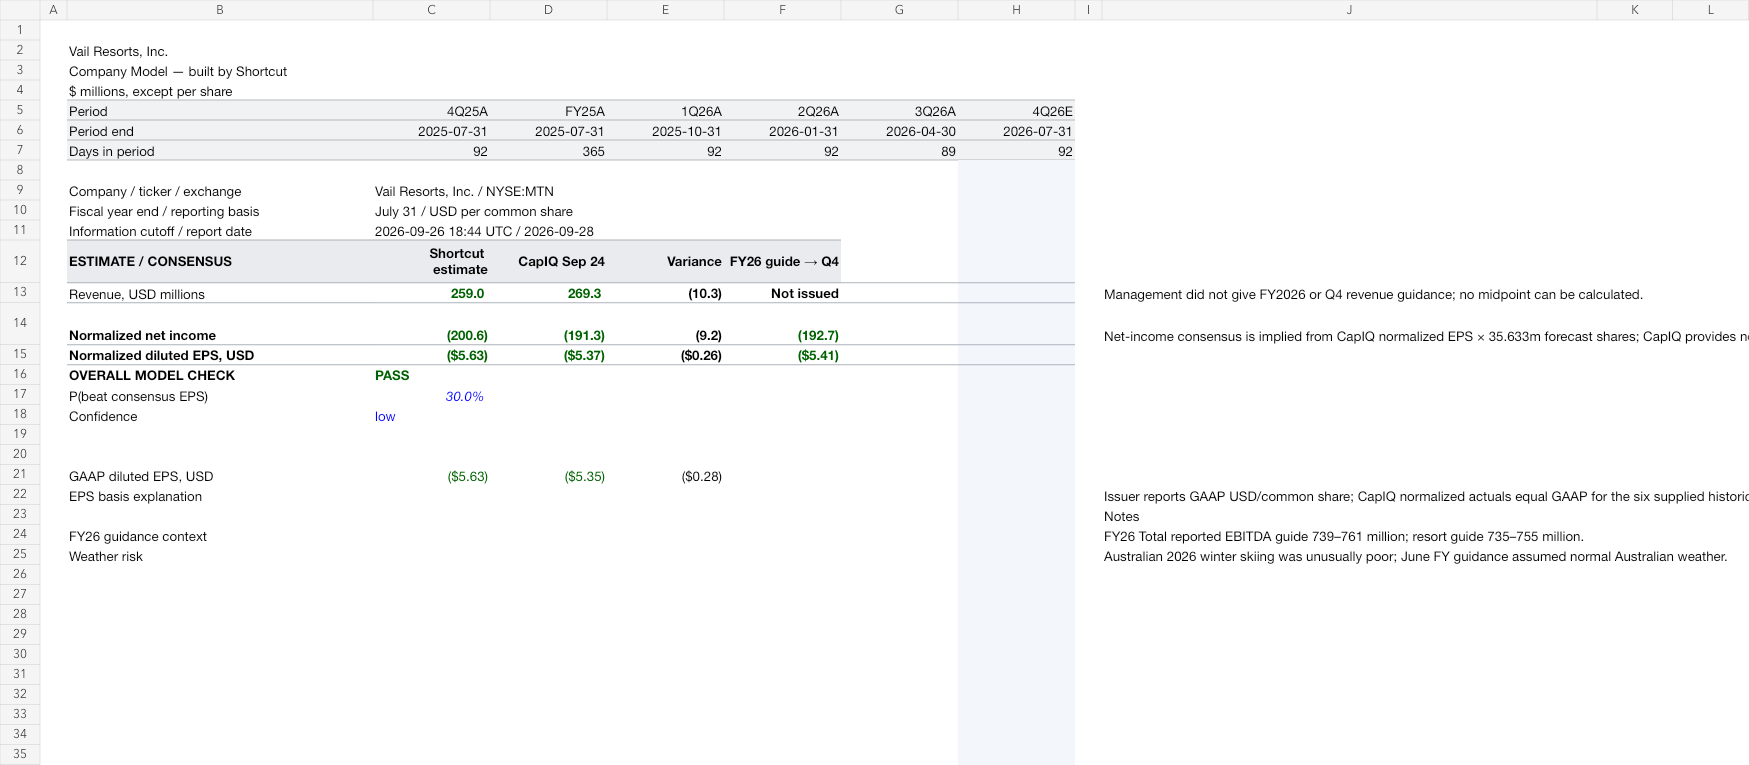
- September 24 normalized consensus is a $5.37 loss on $269.3m of revenue, from ten normalized EPS estimates. Forecast is below the normalized Street estimate, rather than an unearned beat.
- Vail's June 8 FY2026 net-income guidance midpoint implies about -$192.69m, or -$5.41 per Q4 share, after subtracting the reported first nine months. The guide assumes normal Australian ski-season weather.
- ABC reported Australia's warmest alpine winter on record with sparse June/July snow. The September 11 Alpine Observer counted only about 610,000 Perisher visits through the season against a >1m ten-year norm. These observations are after the June guidance and materially challenge the Australian July-quarter sales case, although early pass units were +26% and sales dollars +31% through May 27.
- Product-level mountain revenue of $169.33m (-6.4% Y/Y) plus $89.58m lodging and $0.09m real estate yields $259.00m of Q4 revenue. Forecast net income is -$200.59m, giving normalized diluted EPS of -$5.63 on 35.633m anti-dilutive common shares.
- A September 25 independent earnings preview reported three EPS misses in the four preceding quarters and a negative Earnings ESP. Weak snow-related visits, further interest expense, unknown contingent-consideration marks and jurisdictional tax benefits leave a meaningful probability of a miss despite the advance-commitment model.
- EPS basis: Normalized diluted EPS.
After earnings
Postmortem: why the Street was closer
Against the reported -$5.34 EPS, Shortcut’s -$5.63 forecast missed by $0.29. The published Street estimate of -$5.37 missed by $0.03. The largest contributor was an underestimated tax benefit.
| Q4 FY2026 · USD | Shortcut model | Reported |
|---|---|---|
| Revenue | $259.00m | $278.07m |
| Pre-tax loss | -$261.69m | -$259.96m |
| Income tax benefit | $53.65m | $61.09m |
| Loss allocated to minority interests | $7.45m | $8.71m |
| Net loss attributable to Vail | -$200.59m | -$190.16m |
Tax drove most of the EPS miss
The workbook applied a 20.5% tax-benefit rate to its pre-tax loss. The reported benefit implies about 23.5%. The $7.45m tax-benefit gap accounts for roughly 71% of the $10.44m net-income miss. A $1.73m smaller pre-tax loss and $1.27m more loss allocated to minority interests explain the remainder. Share count was almost exact.
Revenue was too pessimistic, but costs offset much of it
Lodging revenue was $96.22m versus $89.58m modeled. Real estate was $5.99m versus $0.09m. Mountain revenue was $175.86m versus $169.33m. The model anticipated weak Australian skiing, but total revenue finished $19.07m above its estimate. Segment operating costs were also $15.59m above the model, limiting the improvement in profit.
This review compares the original workbook with Vail’s normalized EPS and reported financial results. It explains the displayed result and does not change the original forecast. Model references: Income Statement H14, H23, H34:H43 and H56. Revenue summary H10:H22. Original workbook · Vail earnings release. Figures rounded for display.
The Street baseline: consensus snapshot, September 24, 2026. Results are scored only after the earnings basis is matched. Read the methodology.